The Cost of Waiting
What Another Year of "Safety" Will Actually Cost You
It's mid-January.
The "New Year, New Me" energy is already starting to fade. The gyms are getting quieter. The resolutions are getting blurry. And right about now, a very dangerous thought is creeping into your head:
"I think I'll just play it safe this year. I'll keep my head down, stick to the routine, and wait until things settle down."
It sounds responsible. It feels prudent.
But I'm here to tell you that in 2026, "Safety" is not free. In fact, it is the most expensive subscription service you are currently paying for. 💸
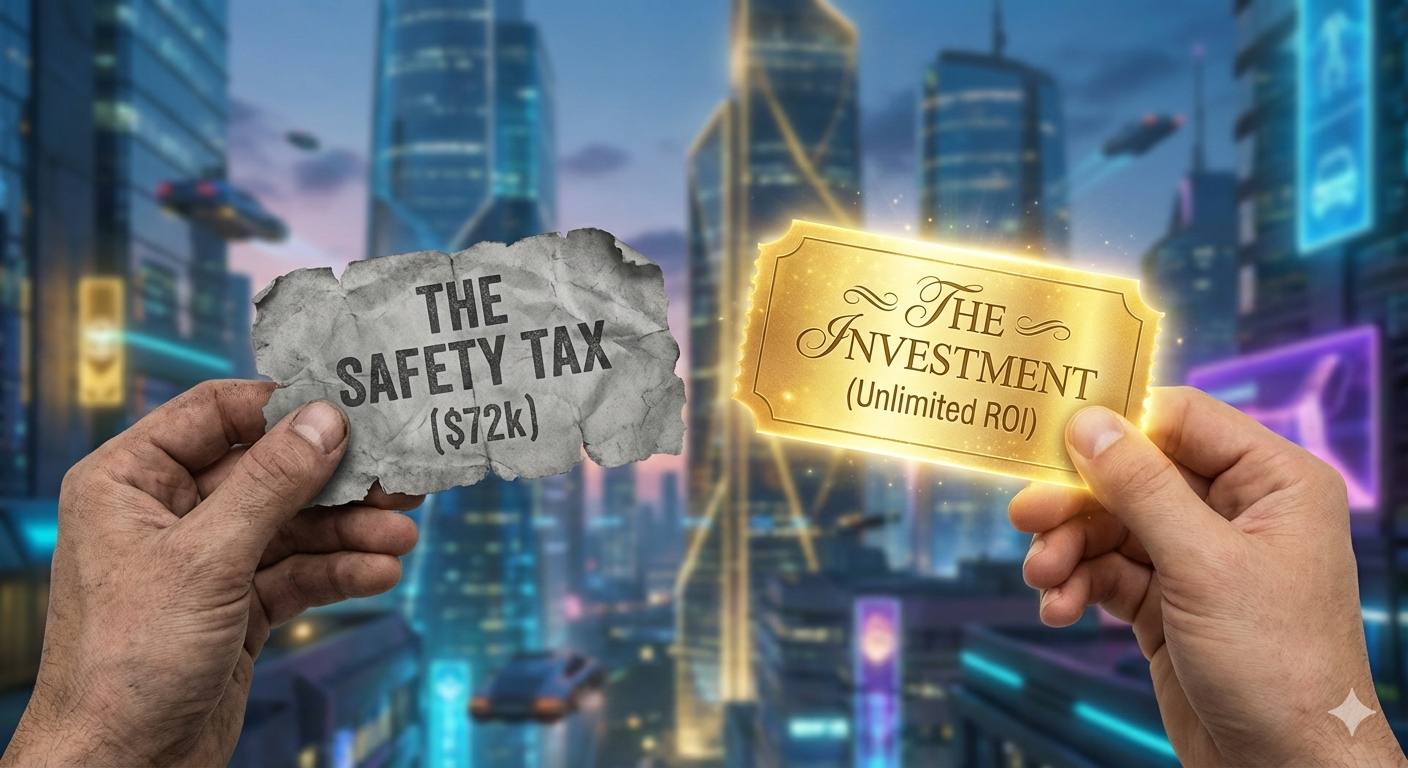
The "Safety Tax"
We are wired to believe that doing nothing costs $0. We think that if we just keep our current job and don't take any risks, our bank account stays neutral.
That is a lie.
You are standing on a moving walkway that is going backward. If you stand still, you aren't staying in the same place. You are moving away from your destination.
Here is the reality of the "Safety Tax" you are paying right now:
📉 The "Personal Inflation" Reality The news loves to celebrate that inflation has "cooled" to around 2.7%. That sounds nice on paper.
But do you eat paper? Do you heat your home with paper?
The things you actually pay for are exploding.
- Energy services are up 7.7%. ⚡
- Natural gas is up 10.8%. 🔥
The cost of existing is rising way faster than the news admits.
📉 The Wage Trap Here is the other side of the equation. In 2025, nearly 50% of workers received exactly $0 in raises.
Zero. Zilch. A big fat nothing. 🚫
So on one side, your expenses are going up 7% or more. On the other side, your income is staying flat. The gap between those two lines is your "Safety Tax." It is the invisible, silent fee you are paying every single month for the privilege of not taking a risk.
Let's do the math. If the average household income is about $80,000 and your real cost of living (accounting for actual inflation on the things you buy) is going up 3-4% per year, you are losing roughly $2,400 to $3,200 in purchasing power annually just by standing still.
Over five years? You are effectively $12,000 to $16,000 poorer than you are today, without a single thing in your life visibly changing. 📉
That is the price of "playing it safe." And you are charged whether you like it or not.
The "Opportunity Vacuum"
But the financial erosion is only half of the cost. The other half is the Opportunity Vacuum.
Every month you wait, the landscape shifts. The funding programs change. The market windows open and close. The "early mover" advantage in our industry doesn't last forever. 📅
Here is a stat that might wake you up: In the business credit space specifically, 0% introductory funding offers are cyclical. They get more or less attractive based on Fed policy, bank competition, and economic conditions. Right now, we are in a window. But that window doesn't stay open forever.
The people who moved in 2020 locked in certain advantages that the people who waited until 2022 could not access. The people who move in 2026 will look back at 2027 and be glad they acted when they did.
Waiting is a decision. And like all decisions, it has a cost. 💸
The "Sunk Cost" of Inaction
Here is the most dangerous thought pattern I see in the people who come to us after years of hesitation.
They say: "I've already waited this long. I might as well wait until [the economy improves / I have more savings / my credit score goes up / the kids go to college / the stars align]."
This is the Sunk Cost Fallacy applied to your own potential. 🧠
The time you've already spent waiting is gone. You cannot get it back. The only question is: What are you going to do starting today?
Every month of inaction is a month you are paying the Safety Tax, missing the Opportunity Window, and falling further behind the people who chose to act.
The bill doesn't stop coming just because you choose not to open it. 📬
The Math of "Now" vs. "Later"
Let me show you what the actual cost of waiting looks like in real numbers.
Scenario A: You start your funding journey today.
You access $50,000 - $150,000 in 0% business funding. You deploy it into a proven revenue-generating strategy. By the end of year one, your business is generating an additional $3,000 - $10,000 per month in revenue.
Over 12 months, that's an extra $36,000 - $120,000 in income that didn't exist before. 📈
Scenario B: You wait another year to "be ready."
You pay the Safety Tax (approximately $3,000+ in lost purchasing power). You miss the current funding window. You lose 12 months of compounding business revenue. You start from the same place next January, except now you are a year older, a year more frustrated, and $72,000+ behind in lost opportunity (the average of Scenario A's potential).
The gap between Scenario A and Scenario B isn't just a number. It is a year of your life. 🗓️
Stop negotiating with your own potential. The bill for "waiting" is already being deducted from your account. The only question is whether you are getting anything in return for paying it.
The math is clear. The window is open. The only variable is you.
Learn More About 7 Figures Funding & The Funding Machine!